Who Keeps the Lights On?
Why energy security now sits at the center of investment and risk analysis
Energy Security and the Investment Outlook
By Lawrence Muscant / Partner, Executive Vice President
Omnia Family Wealth
In Brief
U.S. electricity demand is rising again after two flat decades, driven by artificial intelligence, at the moment supply is contested by force in Ukraine and the Gulf and outbuilt by China.
The binding constraint on AI is power, not chips. Falling short may send computing, manufacturing, and inflation in the wrong direction and hand adversaries leverage that sanctions cannot remove.
Governments have made energy supply state policy, which improves the odds for the companies that build capacity without guaranteeing them. Financing the buildout on top of heavy public debt may weigh on long-term bonds and currencies.
Geopolitical and energy analysis should be an important component of any investment and risk methodology.
Who Will Have Reliable Energy, and at What Cost?
Late on August 31, two oil tankers were struck within minutes of each other in the Strait of Hormuz. The next morning, Fervo Energy announced a long-term agreement to supply Google with geothermal electricity from Utah. That same weekend, Russia announced a renewed campaign of strikes against Ukraine’s power generation ahead of winter.
Each concerns the same question: who will have reliable energy, and at what cost.
Electricity Demand in the United States
After two flat decades, U.S. electricity demand is rising again, driven principally by artificial intelligence, at a moment when two wars are being fought over energy infrastructure, China is adding generating capacity at an unprecedented rate, and governments have concluded that supply can no longer be left to the market alone.
EIA forecasts record U.S. electricity consumption in 2026 and 2027. Data centers accounted for 4.4% of national consumption in 2023, a share the Department of Energy expects to reach 6.7% to 12% by 2028. The four largest technology companies are expected to spend roughly $670-$725 billion in 2026 on data centers, semiconductors, and associated power, up from about $410 billion in 2025. Much of that capital is chasing electricity that does not yet exist.
Continuous Power
Natural gas, nuclear, geothermal
Variable Power
Wind and solar
Mobility
Oil remains essential
The Physical Constraints on Artificial Intelligence
Artificial intelligence is usually discussed as software. For investors, the more pressing point is physical. The binding constraint on AI is no longer the supply of chips but the electricity to run them, the transmission to deliver it, the cooling to remove the heat every chip throws off, and the labor to build all three. Cooling and power delivery add 10% to 50% on top of a facility’s computing load.
The AI Stack Has Become Physical
Compute: Chips and servers
Power: Generation capacity
Grid: Transmission + interconnection
Cooling: Heat removal
Labor: Drillers, electricians, crews
Relieving the Constraint
Continuous Power
Sited next to the computing it serves. Microsoft’s agreement to buy output from a restarted reactor at Three Mile Island illustrates the logic.
Automation
Fervo reported roughly a 70% reduction in drilling time between its first Project Red horizontal well in 2022 and its fastest Cape Station well reported in 2024.
Robotics
Further out, robotics will draw on new electricity and take on a growing share of construction itself.
Energy as a Theater of Conflict
The wars in Ukraine and the Gulf are fought over the energy that exists today; the contest with China is over the energy that has yet to be built. Each travels quickly to a household budget in Miami or Bavaria.
Ukraine
Electricity vs. oil
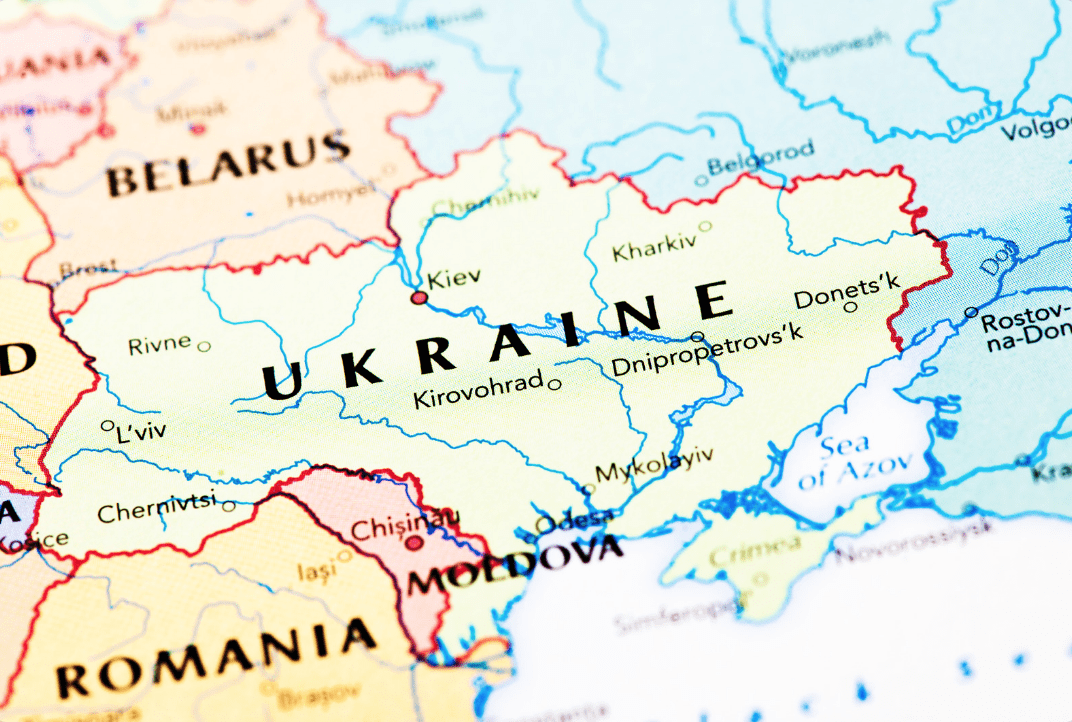
Ukraine’s energy minister estimated in August 2026 that Russia had destroyed or damaged more than 80% of Ukraine’s power generation. Ukraine has answered with long-range drone strikes on Russian refineries and fuel depots. Neither front stays local.
Iran
Hormuz risk premium
The Strait of Hormuz has become a contested waterway. Crude has moved several percent in a single session, and fuel costs and inflation prints have followed.
China
Capacity race
China’s installed capacity is more than triple that of the United States, and in the first half of 2026 it added roughly 160 gigawatts of new generation.
Taiwan
A potential stop, not a shock
TSMC accounts for roughly 90% of the world’s most advanced chip manufacturing. A blockade or invasion would leave data-center capex funding facilities with nothing to put in them.
Energy security is now a portfolio question as much as a policy one.
The Risks of Constrained Supply
The risk of constrained supply is no longer hypothetical. In the mid-Atlantic grid serving 67 million people, the price paid to generators simply to be available at peak demand rose from $28.92/MW-day in the 2024/2025 auction to $329.17/MW-day for 2026/2027 and $333.44/MW-day for 2027/2028. In the latest auction, capacity procured fell 6.5 GW short of PJM’s reliability requirement.
If the U.S. Fails to Build Enough Reliable Supply
The AI Industry Leaves
Computing goes where the electricity is. If it cannot be secured at home, data centers, jobs, and tax base migrate elsewhere.
Reshoring Hits the Grid
Semiconductor, pharmaceutical, and defense production depends on cheap, dependable power.
Costs Rise Across the Economy
Scarce power lifts bills, higher bills feed inflation, inflation keeps rates elevated, and asset values feel the pressure.
Allies Buy From Beijing
If China becomes the principal supplier of reactors and data-center infrastructure, dependence becomes geopolitical leverage.
Adversaries Keep Their Leverage
Domestic generation at home, and diversified supply for allies, are the durable answers.
Energy is national security as much as economics.
The Role of the State
Governments have reached the same conclusion. U.S. energy policy has been reorganized around AI and national security: the White House has invoked the Defense Production Act to declare grid equipment and baseload generation essential to national defense, the federal target is to quadruple nuclear capacity by 2050, federal land is being opened to data centers and the plants that power them, grid operators have been directed to speed connections for large customers, and geothermal has received direct federal cost-sharing and loan support on top of tax credits.
The National Energy Dominance Council
Created by executive order in February 2025 and chaired by Interior Secretary Doug Burgum, the Council has already shaped a January 2026 agreement with mid-Atlantic governors to advance more than $15 billion in new generation, permitting timelines compressed from years to months, and an August 2026 Utah geothermal lease sale that set federal records for highest parcel bid and highest per-acre bid.
State Policy Shifts the Odds
Public funding does not guarantee success and can inflate asset prices, but technologies that once depended on patient venture capital now have federal cost-sharing, expedited permitting, and the government as a customer.
The “Race to the Bottom”
Most Western governments enter this period carrying historically heavy debt just as growth becomes harder to generate, while defense, energy security, semiconductor capacity, AI infrastructure, and the industrial base behind them are treated as unavoidable national-security expenditures.
Strategic spending → More borrowing → Long-bond pressure → Weaker purchasing power
What we expect is a broader decline in the purchasing power of currencies relative to scarce assets, commodities, and productive capacity.
Implications for Portfolios
We draw four conclusions for portfolio construction.
1. Diversify AI Exposure Beyond Technology Equities
We believe parts of the power, infrastructure, and enabling-technology complex may offer attractive opportunities, although valuation, execution risk, liquidity, and technology selection remain critical.
2. Treat Energy as a Hedge, Not a Bet
For appropriate portfolios, a modest, stable allocation to energy and power-related investments may cushion exposure to an energy shock, held through cycles rather than traded on headlines.
3. Hold Assets That Keep Their Value When Energy Costs Rise
Real assets, infrastructure, businesses with pricing power, shorter maturities, floating-rate exposure, and private credit may be more resilient when inflation proves persistent, but liquidity and credit risks matter.
4. Focus on Strategic Exposures
Scarce strategic resources, nuclear and power infrastructure, grid equipment, defense technology, semiconductor manufacturing, and robotics may benefit from strategic necessity as much as scarcity.
Investment views are Omnia’s analysis; see Important Information and Sources & Substantiation.
What This Means for Your Portfolio
Translating the View
If electricity is the constraint on the decade ahead, the portfolio question is what to own, at what price, and when to commit. These conclusions translate into a small number of adjustments. For most clients the work is a review, not a rebuild.
Valuation and the Risk of Arriving Late
A thesis this widely discussed is no secret. Valuations across power and grid equipment, nuclear, and many of the industrial businesses associated with data-center construction have risen significantly. In some areas, current prices appear to assume years of successful execution that have yet to occur. Announced capacity is not built capacity; signed agreements do not deliver electricity; and permitting timelines can compress on paper faster than crews, equipment, and transformers can appear.
That argues for discipline about entry rather than a different conclusion. Three things follow.
1. Separate the Thesis From the Price
We can be right about the direction of electricity demand and still lose money paying too much for it. Where valuations already embed flawless delivery, the risk-reward has moved even though the story has not.
2. Prefer the Parts of the Chain the Market Has Not Crowded Into
Enthusiasm has concentrated in the visible names. The less-traveled exposures, equipment and services layers, private companies solving engineering problems, and assets that benefit from scarcity without requiring a single technology to win, are areas where we are generally more comfortable evaluating new commitments.
3. Build Positions Over Time, Not at Once
Scaling in across vintages and entry points, and holding a reserve for the dislocations this sector reliably produces, may matter more than being early to a theme that is already consensus.
Being late to a crowded trade and being wrong about the underlying shift are different mistakes. We are working to avoid the first while staying positioned for the second.
Conclusions
What the Thesis Makes Us Question
If we are right about the direction of currencies and the persistence of inflation, we become more cautious about long-duration nominal bonds and concentrated positions in businesses whose growth assumptions depend on power they have not yet secured. For each client, shortening nominal duration and broadening concentrated exposures are questions we consider in light of objectives, liquidity needs, tax situation, and risk tolerance.
What It Argues For
For appropriate portfolios, this argues for a modest single-digit allocation to energy and power-related exposures, held through cycles rather than traded on headlines. Real assets, infrastructure, and businesses with pricing power may be appropriate to the mandate. Floating-rate and private credit may replace a portion of fixed nominal exposure for clients for whom liquidity and credit risks are acceptable.
What Would Change Our Mind
A faster buildout than the permitting and labor constraints currently suggest, a durable de-escalation in the Gulf, or a genuine efficiency step-change in computing would each narrow this opportunity. We track the case against as closely as the case for.
The Conversation We Want to Have
In client reviews, we can walk a portfolio through three scenarios, a sustained closure of Hormuz, a hard winter in Europe, and a Taiwan contingency, to identify where the portfolio appears resilient and where vulnerabilities may exist. Where the analysis identifies an uncomfortable exposure, we can discuss whether an adjustment is appropriate for that client.
Portfolio work is a review, not a rebuild.
The Role of Venture Capital
Owning the Technologies That Expand Reliable Supply
Much of the value created in a transition of this scale will go not to established utilities but to the small, private firms that learn to drill faster and deeper, store electricity cheaply, and build the equipment that builds the plants.
Start-ups in geothermal, advanced nuclear, storage, grid technology, drilling, and power management are working on the most important technological bottleneck of the coming decade, and venture is how a portfolio reaches them.
Private valuations have moved too. Capital has followed the same thesis into geothermal, advanced nuclear, and storage, and entry prices are higher than they were two years ago. The dislocation is less extreme than in the listed complex; these are smaller rounds, priced company by company rather than by sector sentiment. But the discount to public enthusiasm is narrower than it was, and we underwrite accordingly.
Geothermal
Advanced Nuclear
Storage
Grid Tech
Drilling
Power Management
Our relationships with specialist technology investors can provide access to opportunities that may not be broadly available through public markets. We size the allocation modestly, spread it across vintages and sectors, and hold each investment to the same scenarios we apply elsewhere. These investments also involve substantial illiquidity, execution risk, technology risk, and the possibility of permanent loss of capital.
Venture and private-market discussion is qualitative. No performance, target return, or model return is presented.
Conclusion
The question of who keeps the lights on will be answered over the next decade.
Energy moves inflation, interest rates, supply chains, and national security at once. We watch it as closely as we watch the Federal Reserve, and we are built to do so: geopolitical analysis is an in-house discipline at Omnia, sharpened by relationships with some of the country’s leading energy experts.
As national security expands to include energy, minerals, and computing, the line between an economic asset and a strategic asset will narrow, and that is where we want a growing portion of the portfolio.
Diversification does not ensure a profit or guarantee against loss. Investing in commodities entails significant risk and is not appropriate for all investors.
Our job is to make sure our clients are on the right side of the answer.
What Is Difficult to Print, Difficult to Replace, and Increasingly Important to the State
That changes what diversification means. When governments compete on currency and spend structurally more, we want to own what governments must spend on – scarce assets, productive capacity, and strategic technologies.
Sources & Substantiation
1. EIA Record Electricity Demand Forecast
Short-Term Energy Outlook, released Sept. 9, 2026; forecasts record U.S. electricity sales/consumption in 2026 and 2027.
https://www.eia.gov/outlooks/steo/report/
2. Data Center Electricity Share
DOE/LBNL report release, Dec. 20, 2024; data centers consumed about 4.4% of U.S. electricity in 2023 and are projected at 6.7% to 12% by 2028.
3. Hyperscaler Capital Expenditures
WSJ/FT reporting in 2026 on large-cap technology company AI/data-center capex; used as a range rather than a precise point estimate.
https://www.wsj.com/tech/ai/big-tech-strikes-gold-with-ai-but-at-a-steep-cost-f6d82a22
4. Three Mile Island / Microsoft PPA
Constellation announced a 20-year power purchase agreement with Microsoft to support restart of Three Mile Island Unit 1, Sept. 20, 2024.
5. Fervo Drilling-Time Reduction
Fervo Energy release, Feb. 12, 2024; reports a 70% reduction in drilling time from its first Project Red horizontal well to its fastest Cape Station well.
6. Ukraine Generation Damage
Russia Matters report card, Sept. 9, 2026; summarizes an Aug. 3, 2026 estimate attributed to Ukraine Energy Minister Denys Shmyhal.
7. China Generation Capacity Additions
China Electricity Council / NEA H1 2026 data; approximately 160 GW of new generating capacity added in the first half of 2026.
https://www.chinapower.org.cn/index.php/detail/460836.html
8. TSMC Advanced-Chip Concentration
Stanford Emerging Technology Review 2026, January 2026; cites TSMC at roughly 90% of global advanced-chip manufacturing.
https://setr.stanford.edu/sites/default/files/2026-01/SETR2026_09-Semi_web-260109.pdf
9. PJM Capacity Pricing and Shortfall
PJM 2025 Annual Report, Markets; 2026/27 auction at $329.17/MW-day and 2027/28 auction short 6,517 MW.
https://services.pjm.com/annualreport2025/markets/
10. Texas Data-Center Pause and Load Forecast
Bloomberg reporting, Aug. 11, 2026; EIA data cut Texas 2027 load-growth estimate from 14% to 5.6% after data-center pause.
11. Mid-Atlantic Generation Agreement
DOE announcement, Jan. 16, 2026; administration and governors urged PJM procurement to build more than $15B of reliable baseload generation.
12. Utah Geothermal Lease Records
Department of the Interior release, Aug. 19, 2026; Utah geothermal lease sale set BLM records for highest parcel bid and highest per-acre bid.
https://www.doi.gov/pressreleases/record-24m-winning-bids-utah-geothermal-leases
Important Information
Omnia Family Wealth, LLC (“Omnia Family Wealth”) is a registered investment advisor with the SEC. Advisory services are only offered to clients or prospective clients where Omnia Family Wealth and its representatives are properly licensed or exempt from licensure.
The information provided is for educational and informational purposes only and does not constitute investment advice and it should not be relied on as such. It should not be considered a solicitation to buy or an offer to sell a security. It does not take into account any investor’s particular investment objectives, strategies, tax status or investment horizon. You should consult your attorney or tax advisor.
The views expressed in this commentary are subject to change based on market and other conditions. These documents may contain certain statements that may be deemed forward looking statements. Please note that any such statements are not guarantees of any future performance and actual results or developments may differ materially from those projected. Any projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such.
For additional information, please visit our website at www.omniawealth.com. For current Omnia Family Wealth information, please visit the Investment Adviser Public Disclosure website at www.adviserinfo.sec.gov by searching with Omnia Family Wealth’s CRD #170909.
Have Questions for An Advisor?
RELATED ARTICLES
THE CATCH-22 OF INVESTING IN ARTIFICIAL INTELLIGENCE
Read More
Webinar Replay: A System Under Strain — War, Energy, and the Global Economic Order
Read More
PRIVATE CREDIT: DATA, DISCIPLINE, AND DIVERSIFICATION
Read More
Omnia Family Wealth’s Michael Wagner Featured on CNBC
Read More
PRIVATE CREDIT: OPPORTUNITY AND THE CRITICAL ROLE OF MANAGER SELECTION
Read More
Risk in Emerging Markets: Lessons from Russia, Turkey, Iran and China
Read More
Rare Earths and Supply Chains: Vulnerabilities Underscore the Need for Economic Shift in US
Read More